
A Smart Trader for Portfolio Management based on Normalizing Flows
Proceedings of the Thirty-First International Joint Conference on Artificial Intelligence. Main Track. Pages 4014-4021.
https://doi.org/10.24963/ijcai.2022/557
Keywords
- Machine Learning: Time-series; Data Streams
- Machine Learning: Deep Reinforcement Learning
- Multidisciplinary Topics and Applications: Finance
Abstract
In this paper, we study a new kind of portfolio problem, named trading point aware portfolio optimization (TPPO), which aims to obtain excess intraday profit by deciding the portfolio weights and their trading points simultaneously based on microscopic information. However, a strategy for the TPPO problem faces two challenging problems, i.e., modeling the ever-changing and irregular microscopic stock price time series and deciding the scattering candidate trading points. To address these problems, we propose a novel TPPO strategy named STrader based on normalizing flows. STrader is not only promising in reversibly transforming the geometric Brownian motion process to the unobservable and complicated stochastic process of the microscopic stock price time series for modeling such series, but also has the ability to earn excess intraday profit by capturing the appropriate trading points of the portfolio. Extensive experiments conducted on three public datasets demonstrate STrader's superiority over the state-of-the-art portfolio strategies.
- [Chen et al., 2018] Ricky TQ Chen, Yulia Rubanova, Jesse Bettencourt, and David Duvenaud. Neural ordinary differ- ential equations. In Proc. of NeurIPS, pages 6572-6583, 2018.
- [Ding et al., 2020] Qianggang Ding, Sifan Wu, Hao Sun, Ji- adong Guo, and Jian Guo. Hierarchical multi-scale gaus- sian transformer for stock movement prediction. In Proc. of IJCAI, pages 4640-4646, 2020. IJCAI
- [Fraccaro et al., 2016] Marco Fraccaro, Søren Kaae Sønderby, Ulrich Paquet, and Ole Winther. Sequential neural models with stochastic layers. In Proc. of NeurIPS, pages 2199-2207, 2016.
- [Grathwohl et al., 2018] Will Grathwohl, Ricky TQ Chen, Jesse Bettencourt, Ilya Sutskever, and David Duvenaud. Ffjord: Free-form continuous dynamics for scalable re- versible generative models. In Proc. of ICLR, 2018.
- [Imajo et al., 2021] Kentaro Imajo, Kentaro Minami, Kat- suya Ito, and Kei Nakagawa. Deep portfolio optimization via distributional prediction of residual factors. In Proc. of AAAI, pages 213-222, 2021.
- [Jiang et al., 2017] Zhengyao Jiang, Dixing Xu, and Jinjun Liang. A deep reinforcement learning framework for the financial portfolio management problem. arXiv preprint arXiv:1706.10059, 2017.
- [Kingma and Ba, 2014] Diederik P Kingma and Jimmy Ba. Adam: A method for stochastic optimization. arXiv preprint arXiv:1412.6980, 2014.
- [Kingma and Dhariwal, 2018] Diederik P. Kingma and Pra- fulla Dhariwal. Glow: Generative flow with invertible 1x1 convolutions. In Proc. of NeurIPS, pages 10236-10245, 2018.
- [Li and Arora, 2019] Zhiyuan Li and Sanjeev Arora. An ex- ponential learning rate schedule for deep learning. arXiv preprint arXiv:1910.07454, 2019.
- [Li and Hoi, 2014] Bin Li and Steven C. H. Hoi. Online portfolio selection: a survey. ACM Computing Surveys, 87(2):1-36, 2014.
- [Li et al., 2020] Xuechen Li, Ting-Kam Leonard Wong, Ricky TQ Chen, and David Duvenaud. Scalable gradients for stochastic differential equations. In Proc. of AISTATS, pages 3870-3882, 2020.
- [Liang et al., 2021] Qianqiao Liang, Mengying Zhu, Xi- aolin Zheng, and Yan Wang. An adaptive news-driven method for cvar-sensitive online portfolio selection in non- stationary financial markets. In Proc. of IJCAI, pages 2708-2715, 2021.
- [Liu et al., 2019] Shikun Liu, Edward Johns, and Andrew J Davison. End-to-end multi-task learning with attention. In Proc. of CVPR, pages 1871-1880, 2019.
- [Liu et al., 2020] Guang Liu, Yuzhao Mao, Qi Sun, Hailong Huang, Weiguo Gao, Xuan Li, Jianping Shen, Ruifan Li, and Xiaojie Wang. Multi-scale two-way deep neural net- work for stock trend prediction. In Proc. of IJCAI, pages 4555-4561, 2020. IJCAI
- [Luo et al., 2018] Rui Luo, Weinan Zhang, Xiaojun Xu, and Jun Wang. A neural stochastic volatility model. In Proc. of AAAI, pages 6401-6408, 2018.
- [Marathe and Ryan, 2005] Rahul R Marathe and Sarah M Ryan. On the validity of the geometric brownian motion assumption. The Engineering Economist, 50(2):159-192, 2005.
- [Moody and Saffell, 2001] John Moody and Matthew Saf- fell. Learning to trade via direct reinforcement. IEEE Transactions on Neural Networks, 12(4):875-889, 2001.
- [Oksendal, 2013] Bernt Oksendal. Stochastic differential equations: an introduction with applications. Springer Science & Business Media, 2013.
- [Rezende and Mohamed, 2015] Danilo Jimenez Rezende and Shakir Mohamed. Variational inference with nor- malizing flows. In Proc. of ICML, pages 1530-1538, 2015.
- [Rubanova et al., 2019] Yulia Rubanova, Tian Qi Chen, and David Duvenaud. Latent ordinary differential equations for irregularly-sampled time series. In Proc. of NeurIPS, pages 5321-5331, 2019.
- [Shi et al., 2019] Si Shi, Jianjun Li, Guohui Li, and Peng Pan. A multi-scale temporal feature aggregation convolu- tional neural network for portfolio management. In Proc. of CIKM, pages 1613-1622, 2019.
- [Veličković et al., 2017] Petar Veličković, Guillem Cucurull, Arantxa Casanova, Adriana Romero, Pietro Lio, and Yoshua Bengio. Graph attention networks. arXiv preprint arXiv:1710.10903, 2017.
- [Wang et al., 2021] Zhicheng Wang, Biwei Huang, Shikui Tu, Kun Zhang, and Lei Xu. Deeptrader: A deep rein- forcement learning approach for risk-return balanced port- folio management with market conditions embedding. In Proc. of AAAI, pages 643-650, 2021.
- [Xu et al., 2020] Ke Xu, Yifan Zhang, Deheng Ye, Peilin Zhao, and Mingkui Tan. Relation-aware transformer for portfolio policy learning. In Proc. of IJCAI, pages 4647- 4653, 2020. IJCAI
- [Ye et al., 2020] Yunan Ye, Hengzhi Pei, Boxin Wang, Pin- Yu Chen, Yada Zhu, Ju Xiao, and Bo Li. Reinforcement- learning based portfolio management with augmented as- set movement prediction states. In Proc. of AAAI, pages 1112-1119, 2020.
- [Yor, 2001] Marc Yor. Exponential functionals of Brownian motion and related processes, volume 112. Springer, 2001.
- [Zhang et al., 2022] Yifan Zhang, Peilin Zhao, Qingyao Wu, Bin Li, Junzhou Huang, and Mingkui Tan. Cost- sensitive portfolio selection via deep reinforcement learn- ing. IEEE Transactions on Knowledge and Data Engineer- ing, 34(1):236-248, 2022.
- [Zhu et al., 2020] Mengying Zhu, Xiaolin Zheng, Yan Wang, Qianqiao Liang, and Wenfang Zhang. Online port- folio selection with cardinality constraint and transaction costs based on contextual bandit. In Proc. of IJCAI, pages 4682-4689, 2020. IJCAI
References were extracted automatically from the PDF and may contain errors.
Full text extracted automatically from the PDF; figures, tables and equations may differ. The PDF is the version of record.
1 Introduction
In financial markets, a stock is often represented as time series consisting of daily open, high, low, and close prices (OHLC) (macroscopic price time series), which is essentially an aggregation of the minute-level OHLC price time series (microscopic price time series). In actual trading practice, such microscopic information is valuable for a portfolio strategy because it provides feasibility to capture trading opportunities, i.e., the near-optimal trading points (TPs), for each stock. Note that a trading point refers to a tradable minute. However, most portfolio strategies [Jiang et al., 2017; Xu et al., 2020; Zhang et al., 2022] pay no attention to such advantage of exploiting microscopic information in deciding the TPs of the daily portfolio, leading to their inabilities in obtaining excess intraday returns. In this paper, we propose a novel problem named trading points aware portfolio optimization (TPPO)
∗Corresponding Author
and aim to design an effective portfolio strategy for this problem to improve the investment's performance.
A TPPO strategy aims to obtain excess intraday profit by deciding the portfolio and its profitable TPs on the target trading day. The decision of TPs relates to the considerations from two aspects, i.e., the trading direction of whether to buy or sell and the minute-level buying and selling points, for each stock. Although the first aspect has been extensively studied [Ding et al., 2020; Shi et al., 2019], the second aspect remains very challenging, which is determined by the microscopic intraday price time series. To be specific, the buying (selling) points of a stock within a day are the microscopic minutes when the stock approximates its lowest (highest) price, which is very difficult to be captured.
Motivating Example. To better investigate the characteristics of TPs, in Figure 1, we plot the microscopic intraday price time series of two stocks in the China market, i.e., Shanghai International Airport Co., Ltd. and China Shenhua Energy Co., Ltd., and their price distributions within each TP. We can make two observations. Firstly, the near-optimal TPs, i.e., appropriate buying or selling points of a stock, are not continuous and may be scattered as depicted in Figure 1(a). In actual practice, there are possibilities that a trading order fails due to accidents such as preemption of transactions or communication failures. This observation indicates that a practical strategy is supposed to find a set containing multiple candidate TPs of each stock. Secondly, as depicted in Figure 1(b), the mean of the minute-level price relative to the daily opening price is constantly shifting and the variance is constantly increasing with the time farther from the daily opening time. Based on this observation, the microscopic price time series is very likely to be governed by a continuous-time process with shifting mean and increasing variance.
Motivated by the above observations, a practical way for portfolio construction with microscopic information is to first model the continuous-time microscopic price time series and then obtain candidate TPs sets based on the modeled series. However, such an idea faces two challenging problems corresponding to the two steps. Firstly, how to model microscopic price time series? (CH1) The distribution that governs the stock microscopic price time series is unobservable, complicated, and ever-changing. What's worst, the discontinuity and irregularity of the price time series hinder the generation of a continuous-time series. Therefore, it is challenging to en- Minute Minute code the series' underlying dynamics and perform continuous extrapolation at arbitrary timestamps. Secondly, how to obtain candidate TPs from the microscopic price time series and construct the portfolio? (CH2) A straightforward idea is to first predict the optimal TP then choose the points close to the optimal point as candidate TPs. However, as illustrated in Figure 1(a), the sub-optimal TPs may not be close, i.e., continuous, to the optimal TP, which makes this naive solution ineffective. Instead, it is necessary to design a ranking mechanism for the construction of candidate TPs sets.
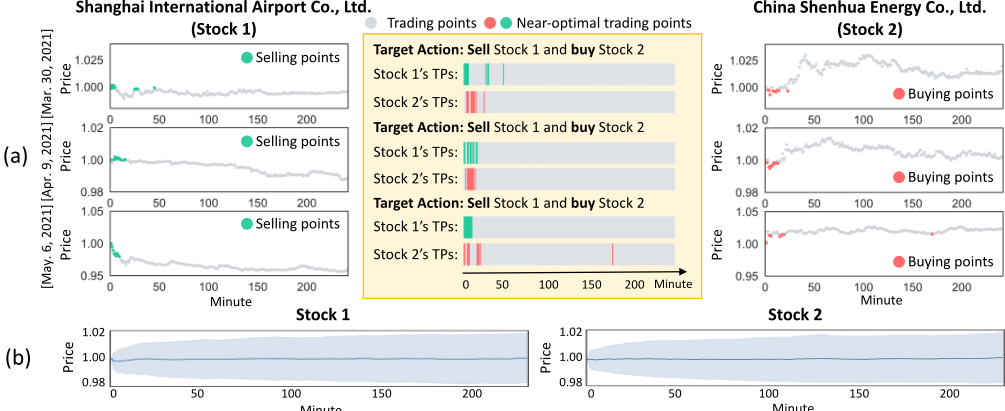
Figure 1: A motivation example that contains (a) the microscopic price time series and the candidate TPs sets, and (b) the price distributions, i.e., mean and variance, of each TP, of two China stocks. Note that each price is normalized by daily open price.
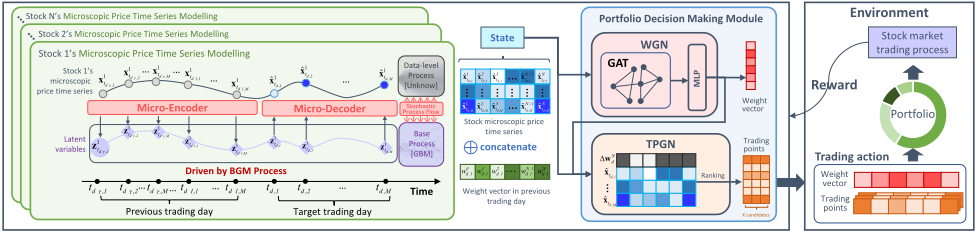
In order to address the above two challenging problems, we propose a novel TPPO strategy, named STrader, derived from normalizing flows, which inherits the superiority of normalizing flows in modeling complex distributions. Overall, our STrader is within the reinforcement learning (RL) framework to model a sequential decision-making process with a state observation process and an action generation process. In the state observation process, we propose a Micro-Encoder and a Micro-Decoder for each stock. Micro-Encoder utilizes our proposed reversible stochastic process flows (SPF) architecture to model a latent geometric Brownian motion (GBM) process, a stochastic process widely used in financial tasks [Yor, 2001; Oksendal, 2013], which governs the latent variables corresponding to the microscopic price time series. Micro-Decoder utilizes the reverse of SPF and the GBM process based on a learnable stochastic differential equation to model the unobservable, complicated, and ever-changing distribution of the price time series and ensure the continuity of the modeled series (for addressing CH1). In the action generation process, our proposed portfolio decision making module computes the portfolio weight and candidate TPs of each stock based on a ranking mechanism, which ranks each TP according to its possibility of being the optimal TP (for addressing CH2). In addition, we design a brand new reward function with TPs for the RL optimization.
Our main contributions are as follows: (1) Problem: We propose an innovative portfolio problem named TPPO, which focuses on deciding both the portfolio weights and trading points for excess intraday returns; (2) Model: We propose a novel TPPO strategy named STrader, which models the microscopic price time series based on normalizing flows and decides the portfolio weights and trading points within the RL framework to address the two challenges. To the best of our knowledge, this is the first attempt to incorporate normalizing flows into stock modeling tasks; (3) Experiment: We have conducted extensive experiments on three real-world datasets, which demonstrate the superiority of STrader over the state-of-the-art portfolio strategies.
2 RelatedWork
2.1 PortfolioManagement
Portfolio management has attracted extensive research focus from the AI community [Li and Hoi, 2014], and it can be categorized into three kinds. The first kind utilizes macroscopic price time series intuitively [Jiang et al., 2017; Xu et al., 2020; Ye et al., 2020; Zhang et al., 2022] without considering the fine-grained microscopic information. The second category exploits both macroscopic and microscopic price time series [Shi et al., 2019; Liu et al., 2020; Ding et al., 2020] to enhance the representation ability, which, however, only focuses on daily portfolio weight allocation and pays no attention to earning the excess intraday profit. The third category incorporates side information, such as market information [Wang et al., 2021], news [Ye et al., 2020] and factor indicators [Imajo et al., 2021] to assist the characterization of sequential features. These strategies need additional information, which is not the focus of our study, and we will study this in our future work.
2.2 Deep Generative Time Series Modeling
The deep generative model has been proven to be effective for time series modeling [Fraccaro et al., 2016; Luo et al., 2018] such as financial series. It can be categorized into three kinds. The first kind is based on variational inference [Luo et al., 2018], which focuses on modeling the distribution of discrete time series without considering the underlying continuous dynamics. The second kind is differential equations based models, which incorporate neural ordinary differential equations [Chen et al., 2018; Rubanova et al., 2019] or latent stochastic process [Li et al., 2020] in the time series modeling framework to ensure the continuity of latent trajectory. However, this kind of method can only handle relatively simple distributions. The third kind is reversible generative models [Rezende and Mohamed, 2015; Kingma and Dhariwal, 2018], which uses normalizing flows
to model a base distribution within each discrete inter-arrival time point and shows promise at capturing complex distributions. In conclusion, none of these three kinds of studies can handle the complexity of distribution and the continuity of time series simultaneously, which hinders their application in modeling stock price time series.
3 Preliminaries and Problem Setting
3.1 Preliminaries
Our portfolio strategy is built upon the GBM process, a continuous-time stochastic process for modeling stock prices in most financial models [Yor, 2001; Marathe and Ryan, 2005]. The generation of GBM relates to the Wiener process and stochastic differential equation (SDE), which we will introduce as follows.
Definition 1 (Wiener Process) A D-dimensional Wiener process W has three properties: (1) W0 = 0; (2) Wt2 -Wt1 ∼ N (0, (t2 - t1)ID) for t1 ≤ t2, and Wt2 -Wt1 is independent of past values of Wt′ for all t′ ≤ t1; (3) when Wt1 = wt1 and Wt2 = wt2 , the conditional distribution for t1 ≤ t ≤ t2 is pWt|Wt1 ,Wt2 (wt | wt1 ,wt2 ) = N (wt;wt1 + t-t1 t2-t1 (wt2 -wt1 ) , (t2-t)(t-t1) t2-t1 Id).
Definition 2 (SDE) An SDE describing the stochastic dynamics of Z usually takes the form dZt = µ(Zt, t) dt + σ (Zt, t) dWt, where Z is a variable which continuously evolves with time, µ(·) is a drift function, σ(·) is a diffusion function, andWt is a Wiener process. For each sample trajectory ω ∼ Wt, the stochastic process Zt maps ω to a different trajectory Zt(ω) = Z0 + ∫ t 0 dZs with initial Z0.
Definition 3 (GBM) Stochastic differential equation (SDE) is often used to model the continuous-time stochastic GBM process because of its ability to add instantaneous noise to the dynamics. The GBM SDE takes the form dZt = µZtdt+ σZtdWt, where µ and σ are the drift and variance terms.
3.2 TPPO Problem Setting
We consider TPPO with N stocks during T trading days, and each day has M minute-level trading points. Each stock has D = 4 kinds of prices, i.e., open, high, low, and close prices.
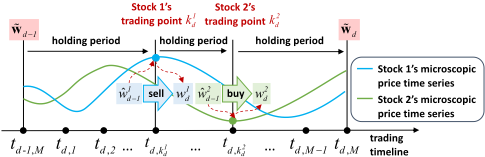
We denote the microscopic intraday prices of stock i in the m-th minute on trading day d as xid,m ∈ RD and denote the prices of all assets on trading day d as xd ∈ RN×M×D . We denote the stocks' microscopic price time series during the previous τ days as xd-τ :d-1 = {xd-τ , ..., xd-1}. For reward calculation, we use the minute-level closing prices, which are defined as pid,m ∈ R and pd ∈ RN×M similarly.
The TPPO process in each trading day d is described in Figure 2, which is formulated within RL framework because of its superior nature in modeling sequential decision making process without annotated data. An Markov Decision Process (MDP) for the RL problem can be defined as a tuple (S, A, T , R), where S denotes a finite state space, A denotes a finite set of actions, T (s′ |s, a) is a state transition function that defines the next state s′ given the current state s and action a, and R(s, a) is a reward function. Moreover, a policy π(a|s) determines an action a given the current state s.
Definition 4 (TPPO formulated as MDP) In each trading day d, a TPPO strategy observes the state sd constructed based on xd-τ:d-1. Based on the state, the strategy determines a portfolio decision πd = (wd, kd) as an action, where wd = (w0 d , w1 d , w2 d , ..., wN d ) is a weight vector with cash weight w0 d and kd = (k1 d , k2 d , ..., kN d ) is its corresponding trading point for each stock satisfying the constraints that w ∈ ∆N = {w|0 ≤ w ≤ 1, w⊤1 = 1} and kd ∈ [1, M]N . Then, the strategy receives a reward rd ∈ R, which is used for portfolio optimization on the next target trading day, and the next state is reached based on sd ∼ T (sd-1, ad-1).
Definition 5 (TPPO reward function) A portfolio decision πd = (wd, kd) in trading day d can be evaluated as
where ct is the transaction cost rate, λ ≥ 0 is a trade-off hyperparameter of transaction cost, ˜wd-1 = wd-1◦rafter d-1 w⊤ d-1 rafter d-1 and
ˆwd-1 = ˜wd-1◦rbefore d ˜w⊤ d-1 rbefore d are the normalized portfolio weights as depicted in Figure 2, and the symbol ◦ denotes the Hadamard product. Note that rbefore d = pd,kd pd-1,M and rafter d-1 = pd-1,M pd-1,kd are the price relative vector before and after trading. According to [Zhang et al., 2022], the transaction cost penalty in Eq.(1) can be used to control the transaction costs.
In this paper, we aim to devise a TPPO strategy to maximize the cumulative reward. Besides, we follow some widely adopted assumptions in portfolio management [Zhu et al.,
| Notation | Description |
|---|---|
| N | total number of stocks |
| T | total number of trading days |
| M | total number of trading points in each day |
| D | total number of prices types |
| xid,m | prices of stock i on the m-th trading point on trading day d |
| xd | prices of all stocks on trading day d |
| xd-τ:d-1 ˆx | prices series during days d-τ to day d-1 predictive prices time series of all assets |
| pd | closing prices of all assets on trading day |
| td,m | d time index of the m-th trading point on |
| T | trading day d state, action, transition, and reward space |
| S,A, ,R | |
| wd kd | portfolio weight vector on trading day d portfolio trading point vector on trading |
| πd | day d portfolio strategy (wd, kd) on trading day |
| rid | d correlation representation for stock i on |
| day d reward of πd = (wd, kd) on trading day d | |
| rd ˜wd, ˆwd | normalized weight vectors on trading day d |
| W,X | Wienie process and observation |
| z,Z | process |
| latent variable and latent process |
Table 1: Notations in the paper.
4 Methodology
4.1 Overall
Our proposed STrader consists of three key modules, i.e., Microscopic Price Time Series Encoder (Micro-Encoder), Microscopic Price Time Series Decoder (Micro-Decoder), and Portfolio Decision Making Module (PDM). STrader's architecture is shown in Figure 3. Specifically, each stock has one Micro-Encoder and one Micro-Decoder. A Micro-Encoder learns a reversible transformation function between the stock price's stochastic process and its latent GBM process. A Micro-Decoder utilizes the inverse of its process transformation function to generate the stock's microscopic price time series in the target trading day d. Based on the generated microscopic price time series, PDM computes the portfolio weight and candidate TPs of each stock. We elaborate the three modules on each day d as follows.
4.2 Microscopic Price Time Series Encoder (Micro-Encoder)
Inherently, an observed microscopic stock price time series is governed by a stochastic process (data-level process), which is, however, unobservable and too complicated to learn. This hinders the modeling of the microscopic series. Inspired by normalizing flows [Rezende and Mohamed, 2015], which is a technique to reversibly transform a simple base distribution into a complex target distribution, STrader aims to find a function for transforming stochastic process in each MicroEncoder. Specifically, STrader regards the GBM process as a base process and learns a reversible process transformation function that transforms the distributions between the datalevel process and the GBM process based on our proposed stochastic process flows, a novel architecture derived from continuous normalizing flows [Grathwohl et al., 2018]. The advantage of such an idea is that the data-level process can inherit many of the appealing properties of the GBM process.
In each Micro-Encoder of stock i, the microscopic price time series xid-τ:d is an incomplete realization of the datalevel process {Xt}t∈[td-τ,1,td,M]. For simplicity, we ignore the superscript i of the notations for stock i and formulate [td-τ,1, td,M] into [t0, ..., tβ, tβ+1, ..., tβ+M], where tβ+1 and tβ+M are the first and last trading points on the target trading day d. The reversible transformation function Fθ(Zt; t) is parametrized by the learnable parameters θ for every trading point t, where Zt is a random variable of the GBM process at time t. Our goal is to model {Xt = Fθ(Zt; t)}t∈[t0,tβ+M] such that the log-likelihood of the observations Ldjoint = log pX0,...,Xβ+M (x0, ..., xβ+M) is maximized. Such Fθ(Zt; t) is approximated as follows.
Stochastic Process Flows Architecture. We define the mapping from observed prices to latent variables using neural ODE based on the instantaneous change of variables formula of Theorem 1 in [Chen et al., 2018]. Given a price vector xt, we compute the latent variable zt that generates xt, as well as log p(xt) by solving the initial value problem in Eq. (2):
where zκ0 t is the base distribution governed by the latent GBM process in t, aκt is a series of time feature vector elaborated in Section 4.3, and f is a Lipschitz continuous function to learn the parameter θ of Fθ. Thus we can compute log p(xt) by adding the solutions with logpzκ0 t (zt). Furthermore, we use the unbiased estimate of the log-density introduced in [Grathwohl et al., 2018] to accelerate the solving process.
Training Goal. The training goal of each Micro-Encoder i in each trading day d is to maximize Eq. (3), which measures the model's ability to fit the microscopic price time series.
4.3 Microscopic Price Time Series Decoder (Micro-Decoder)
In order to generate the microscopic price time series governed by the data-level process, which inherits the properties of the GBM process, we can follow three steps: (1) constructs the GBM SDE; (2) solves the GBM SDE to sample multiple trajectories; (3) transforms the trajectories to the stock price time series. The generated series covers not only the previous trading days (interpolation) for handling the irregularity of the time series but also the target trading day (extrapolation) for portfolio strategy construction.
Firstly, the GBM SDE is constructed based on
where µ and σ are learnable parameters.
Secondly, to sample one trajectory, STrader samples z0 ∼ N(0, 1) as the sample at the first trading point t0, i.e., the initial value in Eq. (4), then solves the GBM SDE to obtain the samples on all subsequent trading points.
Thirdly, STrader transforms the samples on each trajectory to those on the stock price time series by solving Eq. (5) based on the learned θ of Fθ.
where g is a time encoding function, aκ1 t is used in Eq. (2), and ˆxt is the transformed sample at time t.
Multiple generated stock price time series are averaged as the final generated series of one stock.
Training Goal. In each trading day d, the training goal of each Micro-Decoder i aims to minimize Ld,i MSE = ∑β+M t=β+1 (ˆxt - xt)2 /M.
4.4 Portfolio DecisionMakingModule (PDM)
PDM consists of two networks, i.e., weight generating network (WGN) and trading points generating network (TPGN). WGN outputs the target portfolio weight and the portfolio direction. TPGM outputs the candidate TPs of each stock.
Weight Generating Network (WGN). To better guide the portfolio decision making, STrader models the interrelations between stocks by the graph attention network (GAT) [Veliˇckovi´c et al., 2017]. Note that the adjacency matrix in GAT can be characterized by any structural information between stocks. In this paper, we apply the covariance matrix of the price series as the adjacency matrix. Therefore, we feed the generated series and the adjacency matrix into GAT to obtain each stock i's representation rid . Finally, WGN feeds the generated microscopic price time series, stock correlation representations, and previous weight vector into an MLP followed by a softmax activation function to get portfolio weight vector wd for target trading day d. The portfolio direction vector is ∆wd = wd - ˜wd-1.
Trading Points Generating Network (TPGN). Because we need to find a group of TPs for each stock, we design a ranking method to obtain the ranking score of each TP. Considering that the TPs of each stock are related to its trading direction, we feed both the ∆wd and the microscopic price time series to an MLP for score calculation. Then we construct the candidate set with the top K scoring TPs for each stock. During each trading day, we try to trade each stock with its weight as long as the instantaneous time matches those in its candidate TPs set, and if the trading fails, we will not trade until the next candidate TP arrives. The additional money that has not been traded successfully will be held as cash.
Training Goal. PDM's training goal is to minimize the ranking loss in Eq.(6) and maximize portfolio's reward rd in Definition 5.
where scores,j is the score of the j-th predicted TP of the stock s, ¯ P and P are predicted and ground-truth probabilities.
In addition, we adopt a classical policy gradient algorithm [Moody and Saffell, 2001] in RL to train the policy network by maximizing the portfolio reward rd in Eq.(1) earned by adjusting portfolio weights while controlling transaction costs.
4.5 Learning and Optimization of STrader
STrader's learning contains the goals from four aspects, i.e., fitting the distribution of microscopic price time series, generating microscopic price time series, capturing TPs, and earning wealth. We apply a dynamic weight average method [Liu et al., 2019] for overall optimization with the four aspects. Therefore, the total loss function is given as:
where ζ is a learnable weight vector of the four terms.
| Dataset | Training Data Range | Validation Data Range | Test Data Range |
|---|---|---|---|
| DJIA | 01/02/2020 - 03/31/2020 | 04/01/2020 - 04/30/2020 | 05/01/2020 - 07/31/2020 |
| SSE | 01/02/2020 - 11/30/2020 | 12/01/2020 - 12/31/2020 | 01/01/2021 - 06/30/2021 |
| COIN | 01/02/2020 - 11/30/2020 | 12/01/2020 - 12/31/2020 | 01/01/2021 - 06/30/2021 |
5 Experiments
We conduct extensive experiments to answer the following questions: Q1: How does STrader perform on profitability over the trading rounds? Q2: How does STrader perform on reducing risk? Q3: How does STrader perform in addressing the CH1 and CH2? Q4: Whether STrader finds the appropriate TPs for different stocks in a portfolio?
5.1 Experimental Settings
Data Collection. We have collected three up-to-date datasets. DJIA is a U.S. stock market dataset consisting 30 stocks from Dow Jones Industrial Average Index (DJIA). We collected daily and 1-minute intraday historical price data from Alpha Vantage 1 . SSE is a China stock market dataset covering 50 A-share stocks from the SSE 50 index. The historical daily and intraday price data were collected from iFinD 2 . COIN is a cryptocurrencies market dataset containing 12 different cryptocurrencies, each of which has daily and 1-minute intraday historical price data from coinbase 3 . All three datasets were divided into non-overlapping training/validation/test sets as described in Table 2. Results on all experiments are averaged over 10 runs.
Baselines. Six baselines classified into two groups and two ablation strategies are compared in our experiments:
(1) Macro information based portfolio strategies: EIIE [Jiang et al., 2017] is a conventional RL portfolio strategy utilizing stock historical prices. RAT [Xu et al., 2020] is a state-of-the-art RL strategy with attention on stock price series. PPN [Zhang et al., 2022] is a state-of-the-art RL portfolio strategy focusing on reducing transaction cost.
(2) Micro information based portfolio strategies: EI3 [Shi et al., 2019] is a state-of-the-art portfolio strategy to integrate multi-scale price as states of RL. MTDNN [Liu et al., 2020] is a state-of-the-art wavelet-based deep learning method classifying stock price movements, and we modify this method by trading the stocks where prices are expected to rise. HMGTF [Ding et al., 2020] is a state-of-the-art portfolio strategy to learn hierarchical features of high-frequency finance data.
(3) Simplified versions of STrader: STrader-w/o-SPF is STrader without the SPF architecture, which means that it regards the realization of the GBM process as the predicted stock price process. STrader-w/o-TP is STrader without considering TPs, which means that every stock is traded at the opening time of the target trading day.
Metrics. We use six standardmetrics [Liang et al., 2021] to measure portfolios' performance. Cumulative wealth (CW) and Annualized Percentage Yield (APY) measure the portfolios' returns. Maximum drawdown (MD) and Annualized Volatility (AVO) measure the portfolios' risks. Annualized Sharpe Ratio (ASR) and Calmar ratio (CR) measure the riskadjusted returns. Overall, higher CW, APY, ASR, and CR values indicate better performance, while lower MD and AVO values indicate better performance. Note that if the APY is negative, the ASR and CR cannot be used as comparable metrics and thus are not reported in our following experiments.
1 https://www.alphavantage.co/
2 http://quantapi.10jqka.com.cn/
3 https://developers.coinbase.com/api/
Implement Details. To model real-world markets, we set the transaction cost rate to be 0.25% [Zhang et al., 2022]. We set τ = 1 as the time window size for STrader and τ = 5 for other baselines that are not applicable to intraday trading. We set b = 32 as the batch size. We implement all experiments by using PyTorch and conduct the experiments on an NVIDIA RTX 3090 GPU. We adopt Adam optimizer [Kingma and Ba, 2014] and vary the learning rate of the network in {10-2 , 10-3 , 10-4 } by using an exponential learning rate scheduler [Li and Arora, 2019] with a decay rate of 0.01. We vary the size of latent variable hz ∈ {32, 64, 128}, We use two MLP model as fθ and gϕ respectively. We vary the hidden layer in fθ network as lf ∈ {2, 3, 4} with the hidden size hf ∈ {32, 64, 128}, and the hidden layer in gϕ network as lg ∈ {2, 3, 4} with the hidden size hg ∈ {32, 64, 128}. We vary the number of attention heads in GAT as lGAT ∈ {2, 3, 4}, and the dimension of the feature space in GAT as hGAT ∈ {32, 64, 128}. We vary the size of top-K in timeaware rank loss K ∈ {10, 20, 30}. Besides, we set the parameters of the baselines to be the optimal values reported in their publications because the optimal parameters of each baseline do not distinguish between datasets according to their publications. We tune parameters based on the validation dataset and evaluate performance on the test dataset.
5.2 Performance Comparison and Analysis
Result 1: Performance on Profitability. To answer question Q1, we compare the performance of STrader and the six baselines on CW and APY (cf. Table 3). STrader achieves the highest CW and APY values with average improvements of 7.541% and 72.529%, respectively, over the best-performing baselines. The results demonstrate the effectiveness of STrader from two aspects. First, STrader outperforms all macro information based strategies because it additionally models the microscopic price time series based on the novel stochastic process flow architecture to assist portfolio decisions. Second, STrader outperforms all micro information based strategies because they overlook excess intraday profit, whereas STrader leverages the microscopic information for appropriate TPs decisions and earns more profit.
Result 2: Performance onRisk. To answerQ2, we present the risk, i.e., MD and AVO, achieved by STrader and the six baselines in Table 3. STrader is among the best three out of all seven strategies. It is comparable to all baselines from the following three perspectives. First, STrader achieves the lowest MD, demonstrating that STrader can resist drawdown risks. Second, although STrader has a larger AVO than the best-performing baselines, such results are insignificant with their p-values > 0.05 on DJIA and COIN datasets, indicating that this not-so-good result is accidental. Such results can be tolerated for a risk-insensitive method. Third, high risk comes with high returns. If we take the return and risk into consideration simultaneously, i.e., estimating ASR and CR (cf. Table 3), STrader performs the best, indicating its outstanding ability in balancing return and risk.
| DJIA | SSE | COIN | ||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| Categories | Strategies | CW | APY | ASR | CW | APY | ASR | CW | APY | ASR |
| Market | Index 4 | 1.086 | 0.375 | 1.423 | 0.993 | -0.015 | - | 7.523∗ | 56.225∗ | 30.546 |
| Macro information based portfolio strategies | EIIE RAT PPN | 1.070 ± 0.002 1.062 ± 0.009 1.098±0.026∗ | 0.300 ± 0.007 0.263 ± 0.042 0.438±0.128∗ | 1.253 ± 0.005 1.122 ± 0.083 2.137±0.379∗ | 0.982 ± 0.001 1.033 ± 0.076 1.035±0.045∗ | -0.036 ± 0.001 0.071 ± 0.167 0.074±0.097∗ | - 0.312±0.733∗ 0.212 ± 0.171 | 5.753 ± 3.312 5.699 ± 0.718 7.295 ± 0.036 | 33.880 ± 48.302 10.146 ± 1.973 52.800 ± 0.535 | 21.613 ± 14.704 7.675 ± 1.064 33.409 ± 0.456∗ |
| Micro information based portfolio strategies | EI3 MTDNN HMG-TF | 1.070 ± 0 1.076 ± 0 1.094 ± 0.011 | 0.299 ± 0 0.327 ± 0 0.416 ± 0.053 | 1.253 ± 0 1.258 ± 0 1.543 ± 0.128 | 0.982 ± 0 0.981 ± 0 1.019 ± 0.011 | -0.037 ± 0 -0.039 ± 0 0.040 ± 0.022 | - - 0.170 ± 0.095 | 4.503 ± 8.010 4.956 ± 0 6.261 ± 1.118 | 29.311 ± 128.438 23.784 ± 0 38.922 ± 13.234 | 9.785 ± 25.710 17.298 ± 0 27.418 ± 9.234 |
| STrader (Our) | STrader STrader-w/o-SPF STrader-w/o-TP | 1.117±0.001 1.110 ± 0.002 1.073 ± 0.001 | 0.533±0.006 0.498 ± 0.013 0.314 ± 0.006 | 2.411±0.027 2.283 ± 0.059 1.250 ± 0.023 | 1.088±0.005 1.008 ± 0.001 0.981 ± 0.001 | 0.191±0.012 0.017 ± 0.002 -0.039 ± 0.001 | 0.973±0.065 0.095 ± 0.011 - | 8.711 ± 3.561 7.685 ± 1.345 4.503 ± 0.119 | 77.917±73.771 59.127 ± 22.412 19.446 ± 1.073 | 55.796±40.403 44.467 ± 13.393 15.306 ± 0.778 |
| Improvement 5 p-value 6 | 1.699 0.004 | 21.690 0.004 | 12.822 0.002 | 5.137 0.000 | 157.317 0.000 | 212.008 0.000 | 15.787 0.024 | 38.581 0.034 | 67.011 0.001 | |
| DJIA | SSE | COIN | ||||||||
| Categories | Strategies | CR | MD | AVO | CR | MD | AVO | CR | MD | AVO |
| Market | Index 4 | 4.040 | 0.093 | 0.263 | - | 0.156 | 0.206 | 84.771 | 0.663 | 1.841 |
| Macro information based portfolio strategies | EIIE RAT PPN | 3.545 ± 0.011 3.133 ± 0.272 5.204±1.376∗ | 0.085 ± 0.002 0.084 ± 0.007 0.084 ± 0.003 | 0.239 ± 0.006 0.234 ± 0.022 0.203±0.027∗ | - 0.527±1.144∗ 0.290 ± 0.217 | 0.127±0.002∗ 0.147 ± 0.050 0.245 ± 0.093 | 0.177±0.003∗ 0.225 ± 0.059 0.338 ± 0.148 | 54.836 ± 76.933 16.403 ± 3.183 98.254 ± 0.664∗ | 0.616 ± 0.013 0.618 ± 0.004 0.537 ± 0.002∗ | 1.502 ± 0.761 1.319 ± 0.068∗ 1.580 ± 0.008 |
| Micro information based portfolio strategies | EI3 MTDNN HMG-TF | 3.547 ± 0 3.564 ± 0 4.935 ± 1.061 | 0.084 ± 0∗ 0.092 ± 0 0.085 ± 0.01 | 0.238 ± 0 0.260 ± 0 0.270 ± 0.026 | - - 0.227 ± 0.127 | 0.128 ± 0 0.134 ± 0 0.176 ± 0.015 | 0.178 ± 0 0.188 ± 0 0.234 ± 0.015 | 45.005 ± 183.354 38.495 ± 0 63.666 ± 23.186 | 0.630 ± 0.100 0.618 ± 0 0.612 ± 0.028 | 3.166 ± 2.046 1.375 ± 0 1.418 ± 0.074 |
| STrader (Our) | STrader STrader-w/o-SPF STrader-w/o-TP | 6.576±0.079 6.202 ± 0.168 3.538 ± 0.074 | 0.081 ± 0.001 0.080±0.001 0.089 ± 0.001 | 0.221 ± 0.001 0.218 ± 0.001 0.251 ± 0.001 | 1.857±0.148 0.144 ± 0.016 - | 0.103±0.003 0.121 ± 0.001 0.132 ± 0.001 | 0.196 ± 0.001 0.184 ± 0.001 0.184 ± 0.001 | 150.563±141.275 112.113 ± 41.560 33.291 ± 1.848 | 0.517±0.014 0.527 ± 0.013 0.584 ± 0.002 | 1.373 ± 0.204 1.325 ± 0.084 1.270 ± 0.006 |
| Improvement 5 p-value 6 | 26.367 0.000 | 3.335 0.000 | -8.917 0.474 | 252.251 0.000 | 19.196 0.000 | -10.516 0.000 | 53.239 0.000 | 3.759 0.000 | -4.050 0.100 | |
Result 3: Ablation Study. To answer Q3, we conduct ablation experiments with two simplified versions of STrader (cf. Table 3). Firstly, STrader outperforms STrader-w/o-SPF on CW with an average improvement of 7.279%, which indicates STrader's superiority to model microscopic price time series with a complex stochastic process to address the CH1. Secondly, STrader outperforms STrader-w/o-TP on CW with an average improvement of 36.136%. Ignoring the TPs makes STrader unable to obtain the excess intraday return, which is consistent with the analysis of CH2.
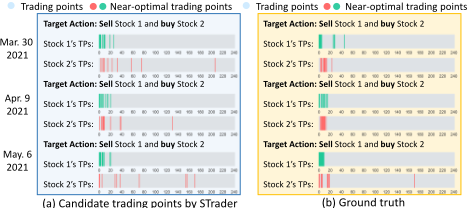
Result 4: Portfolio Qualitative Analysis. To answer Q4, we conduct a qualitative analysis of the two stocks that we have described in our motivating example. Figure 4 depicts the candidate TPs sets decided by STrader and their comparison to the ground truth ones. The results indicate that STrader can indeed find the appropriate buying points and selling points for the stocks expected to buy and sell respectively because STrader models their microscopic price time series precisely. In addition, to validate how well STrader approximates the exact appropriate TPs, we calculate the recall on deciding TPs of our strategy normalized by that of the random sample strategy. Recall of each strategy is recall = 1 NT ∑i∈[N],d∈[T ] |T 10 i,d |∩|Ti,d| |Ti,d| , where T 10 i,d is the candidate TPs set of size 10 predicted by a strategy and Ti,d is the top 10 daily optimal TPs set of stock i on day d. The results of the normalized recall are 2.68, 1.12, and 1.34 on DJIA, SSE, and COIN, respectively. Combining the qualitative analysis and the ablation study results, we can conclude that STrader has outstanding ability in deciding appropriate trading points for earning intraday profit.
4 The index is DJIA (ˆDJI) in DJIA dataset, and SSE 50 (000016.SH) in SSE dataset. The index in COIN dataset is the average return on 12 cryptocurrencies.
5 Improvement of STrader over the best-performing baselines.
6 Statistically not different from the best-performing baselines if p-value < 0.05 (p-value with paired t-test).
6 Conclusions and FutureWork
In this paper, we first propose an innovative portfolio problem named TPPO, then propose a novel strategy named STrader to address two challenging problems in modeling the microscopic price time series and deciding the trading points. Empirical studies demonstrate the effectiveness of STrader. In the future, we plan to extend our work in two potential directions. The first direction is to further incorporate side information to improve the ability to generate microscopic price time series for STrader. The second direction is to model multi-day microscopic time series, which are discontinuous due to price jumps between days.
Acknowledgments
This work was supported in part by the National Natural Science Foundation of China (No.62172362), Leading Expert of "Ten Thousands Talent Program" of Zhejiang Province (No.2021R52001), and the cooperation project of MYbank, Ant Group.
@inproceedings{ijcai2022p557,
  title     = {A Smart Trader for Portfolio Management based on Normalizing Flows},
  author    = {Yang, Mengyuan and Zheng, Xiaolin and Liang, Qianqiao and Han, Bing and Zhu, Mengying},
  booktitle = {Proceedings of the Thirty-First International Joint Conference on
               Artificial Intelligence, {IJCAI-22}},
  publisher = {International Joint Conferences on Artificial Intelligence Organization},
  editor    = {Luc De Raedt},
  pages     = {4014--4021},
  year      = {2022},
  month     = {7},
  note      = {Main Track},
  doi       = {10.24963/ijcai.2022/557},
  url       = {https://doi.org/10.24963/ijcai.2022/557},
}
TY - CPAPER TI - A Smart Trader for Portfolio Management based on Normalizing Flows AU - Yang, Mengyuan AU - Zheng, Xiaolin AU - Liang, Qianqiao AU - Han, Bing AU - Zhu, Mengying T2 - Proceedings of the Thirty-First International Joint Conference on Artificial Intelligence, IJCAI-22 PB - International Joint Conferences on Artificial Intelligence Organization PY - 2022 SP - 4014 EP - 4021 DO - 10.24963/ijcai.2022/557 UR - https://doi.org/10.24963/ijcai.2022/557 ER -Copied
Machine-readable versions of this paper, for tools and AI agents:





